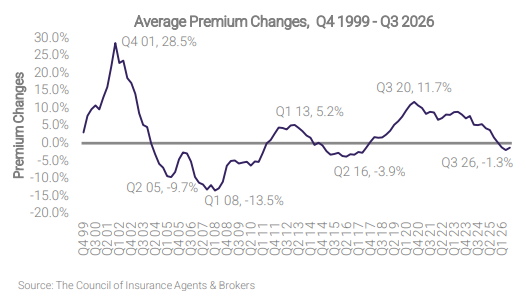
Q3 2026 reinforced the soft market conditions seen earlier in the year, with continued premium decreases across most account sizes and lines of business, though at a moderated pace compared to Q2. According to The Council of Insurance Agents & Brokers’ (CIAB) Commercial P&C Market Index for Q3 2026 (July 1 – September 30), average premiums across all account sizes decreased by 1.3%, an improvement from the 2.0% decline in Q2. Large accounts experienced the steepest decline at 3.1%, while medium and small accounts saw more modest decreases of 0.7% and 0.2%, respectively.
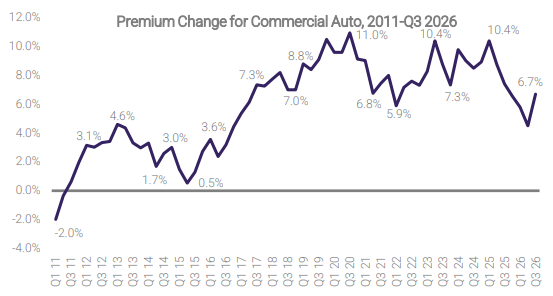
This ongoing softness reflects increased carrier competition and willingness to compromise on pricing to secure business. Despite this, premiums for major lines collectively rose by 0.6%, primarily driven by commercial auto, which posted a 6.7% increase — marking the 61st consecutive quarter of premium growth for this line. Below, we review the key premium changes by line of business and highlight notable trends in commercial property.

Premium Changes by Line of Business
Other notable rate changes in Q3:
- Umbrella (+2.8%)
- Workers Compensation (-3.6%)
- Cyber (-0.2%)
- Commercial Auto (+6.7%)
Commercial Auto Premiums Rise Amid Ongoing Challenges
Commercial auto premiums increased by 6.7% in Q3 2026, marking the 61st consecutive quarter of growth. Despite some of the most favorable underwriting results in the past decade, the line posted an overall underwriting loss of approximately $2.2 billion in 2025, with a combined loss ratio of 102.7%.
Social inflation and nuclear verdicts continue to drive losses, fueled by increased legal representation, aggressive plaintiff strategies, and higher repair costs for advanced vehicle technology. This challenging environment is reflected in the rising claims frequency reported by nearly 40% of respondents, up from 30% in the previous quarter.
Directors & Officers (D&O) Premiums Continue to Decline on Soft Market Conditions
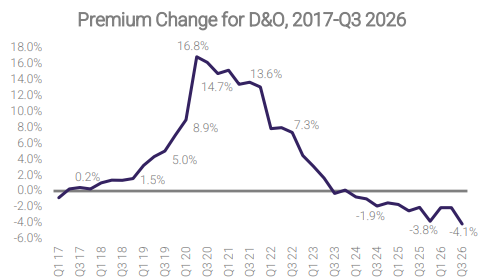
Directors & Officers (D&O) premiums fell 4.1% in Q3 2026, marking the 11th consecutive quarter of decreases and nearly doubling the decline seen in Q2. The softened market is driven by abundant capacity, favorable loss ratios, and more refined risk selection. Additionally, a slight drop in securities class-action lawsuits and reduced regulatory enforcement, including the SEC’s withdrawal from defending its climate disclosure rule, have eased pressures on the D&O market.
For a consultative approach to navigating coverage and pricing changes within the insurance market, contact a UNICO Advisor.
For more information, download the full report below.
The Council of Insurance Agents & Brokers’ Commercial Property/Casualty Market Report Q2 2026. Readers should contact legal counsel or an insurance professional for appropriate advice.